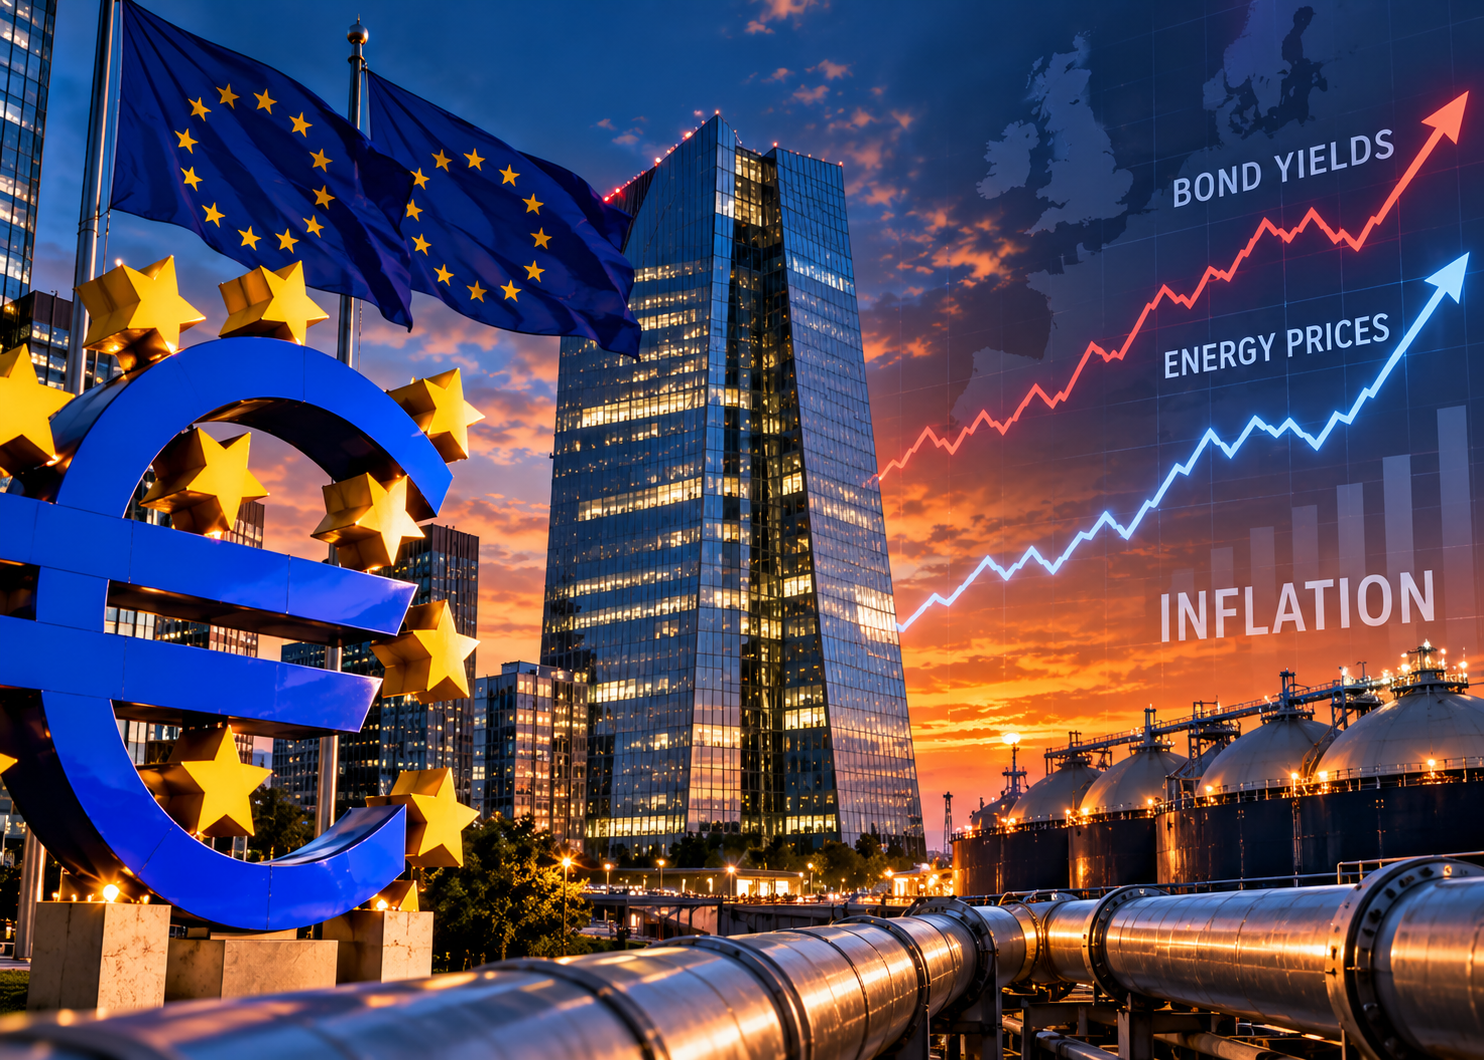
Rising long-term borrowing costs could partly restrain the broader inflationary impact of Europe’s energy shock by slowing economic growth and limiting the transmission of higher energy prices into wages and other prices, according to European Central Bank policymaker Olli Rehn.
Energy prices are moving closer to levels contemplated under the ECB’s adverse inflation scenario as the Middle East conflict continues to pressure global energy markets.
Euro-area inflation has already moved above 3% and could approach 4% by year-end, increasing pressure on the ECB after two rate increases during the summer.
But Rehn, who heads Finland’s central bank, pointed to a countervailing force: sharply higher bond yields.
Germany’s 10-year government borrowing cost recently reached approximately 3.57%, a 17-year high, while the comparable U.S. Treasury yield climbed above 5.3%.
Higher long-term rates tighten financial conditions independently of additional central-bank action.
More expensive financing can reduce investment, weaken demand and slow economic growth. That, in turn, can make it more difficult for the initial increase in energy costs to spread into wages and prices across the broader economy.
The mechanism matters for the ECB because policymakers cannot directly control the international price of oil or natural gas.
Their concern is whether an external energy shock develops into persistent domestic inflation through wages, services and inflation expectations.
The surge in global borrowing costs therefore complicates the ECB’s policy calculation.
Additional rate increases could be necessary if energy inflation continues spreading through the economy, but financial markets are already imposing substantially tighter borrowing conditions on governments, companies and households.
Rehn also identified another potential risk arising from the artificial-intelligence investment boom.
Heavy borrowing by technology companies is increasing competition for global capital, while elevated AI-related valuations create the possibility that a sharp market correction could spread through equity and credit markets.
For investors, the key question is whether elevated bond yields ultimately perform part of the ECB’s inflation-fighting work—or whether persistent energy inflation forces policymakers to tighten monetary policy further despite already restrictive financial conditions.