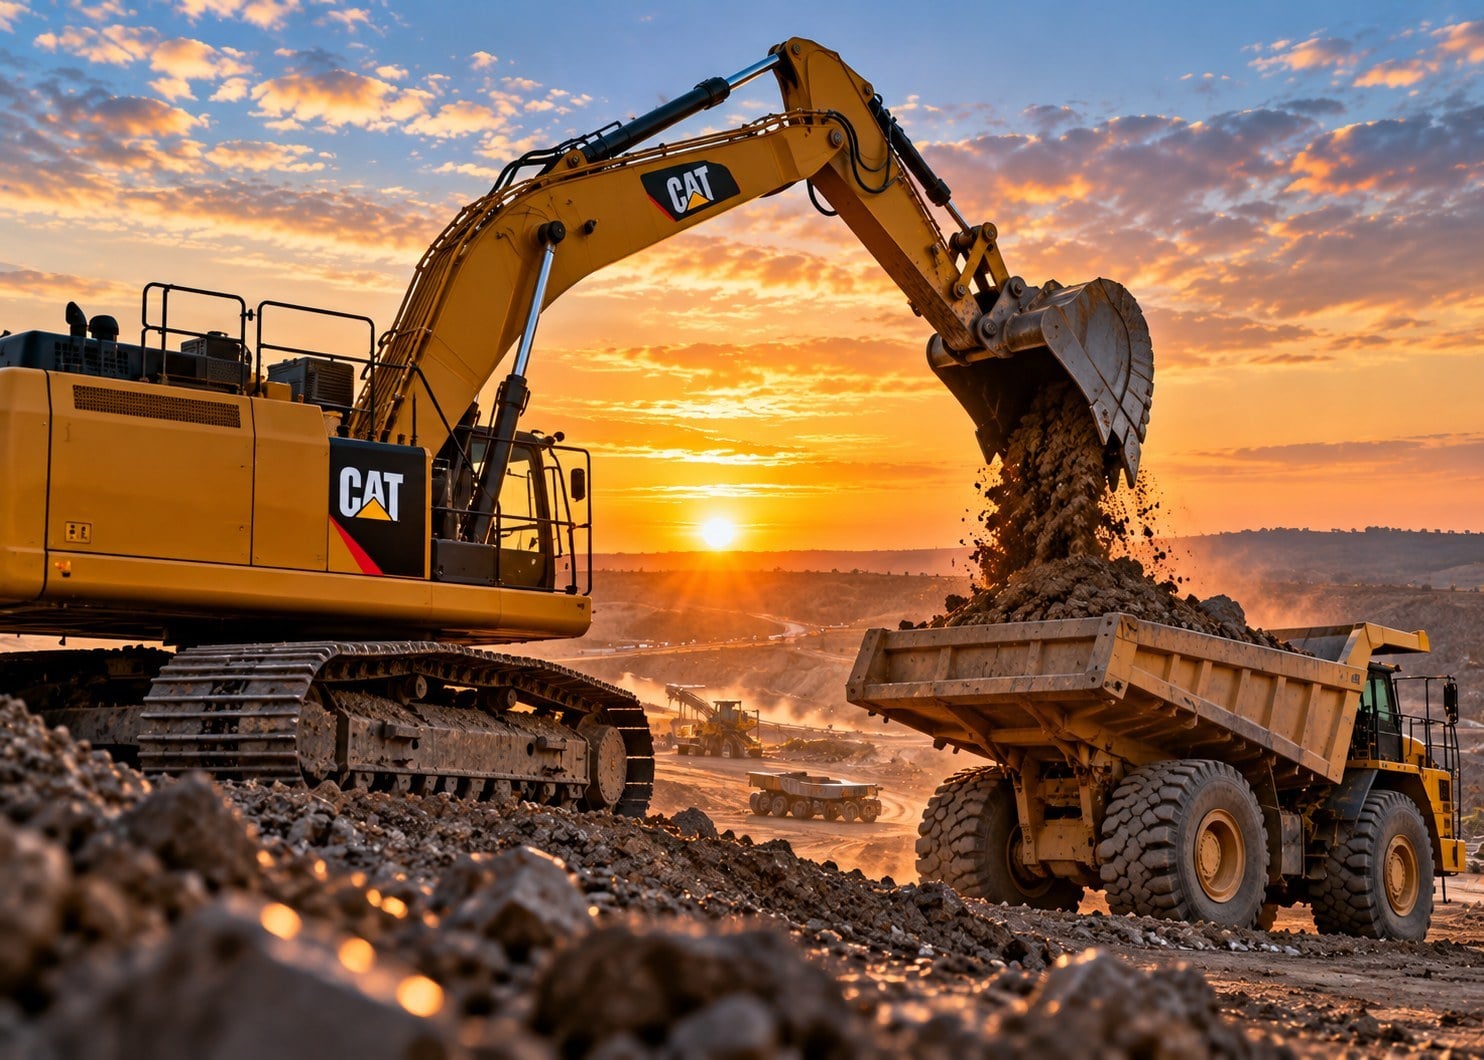
Caterpillar reported sharply higher third-quarter earnings and a record order backlog Thursday, but its shares fell as investors focused on cost pressures and a more restrained growth outlook.
Sales and revenue increased 17% from a year earlier to $20.7 billion. Adjusted earnings reached $7.20 per share, up from $4.95 a year earlier.
Operating profit increased 38% to $4.21 billion, while adjusted operating margin rose to 20.6%.
Demand remained particularly strong in Power & Energy, where revenue increased 18% to $8.78 billion. Construction Industries sales also rose 18%, while Resource Industries increased 15%.
The company’s backlog reached a record $78.1 billion, supported partly by demand for generators and other power equipment used by rapidly expanding data centers.
That exposure has made Caterpillar one of the industrial beneficiaries of the AI infrastructure boom, as large computing campuses require backup generation, turbines, construction machinery and other heavy equipment.
The market reaction, however, showed that investors are demanding more than strong current results.
Caterpillar shares fell sharply as the company maintained its annual revenue-growth forecast in the mid- to high-teens and indicated that fourth-quarter growth would moderate. Tariffs and elevated diesel prices are also increasing costs.
The company continues to estimate roughly $2.2 billion in tariff-related costs for the year, although the third quarter included $128 million of tariff recoveries.
The divergence between record backlog and falling shares highlights a broader shift in the AI investment cycle: investors increasingly want evidence that enormous infrastructure demand can translate into sustained earnings growth without disproportionate cost pressure.
The next test will be Caterpillar’s ability to convert its backlog into revenue while expanding manufacturing capacity and protecting margins.