Wall Street is entering the final quarter of 2026 near record territory, but the combination of historically high Treasury yields, enormous artificial-intelligence spending and an approaching earnings season is creating a critical test for a U.S. equity rally that has pushed the S&P 500 up nearly 13% this year.
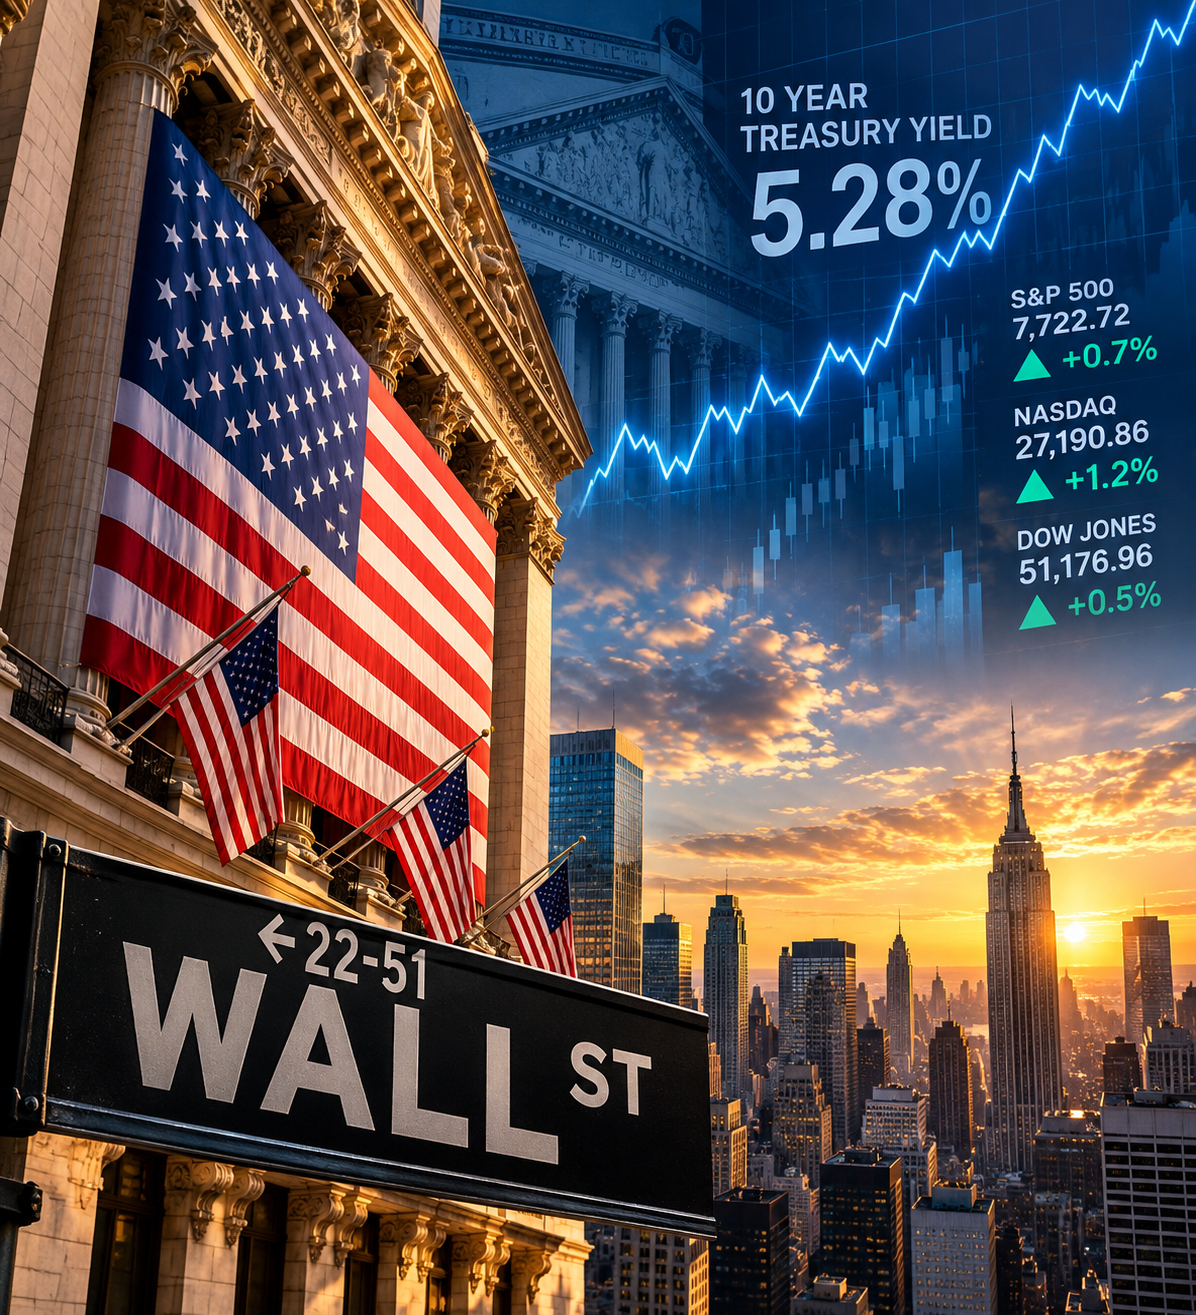
The S&P 500 finished Friday at 7,722.72, up 0.7% for the session and approximately 1% below its August record. The Nasdaq Composite gained 1.2% to 27,190.86, while the Dow Jones Industrial Average advanced 0.5% to 51,176.96.
Friday’s gains followed the weaker September employment report, which reduced expectations that the Federal Reserve will raise interest rates again at its October meeting.
But the bond market delivered a different message.
The benchmark 10-year Treasury yield climbed back to approximately 5.28% Friday, one day after reaching 5.34% — its highest level in 24 years.
That creates an increasingly difficult valuation environment for stocks.
Higher Treasury yields raise borrowing costs throughout the economy while simultaneously increasing the return investors can earn from government debt. The higher those yields rise, the greater the earnings growth companies must produce to justify elevated equity valuations.
Artificial intelligence sits at the center of that equation.
Massive spending by hyperscalers on data centers, chips, power infrastructure and computing capacity has become one of the principal drivers of U.S. corporate investment and stock-market performance.
Investors are therefore preparing to scrutinize capital-expenditure forecasts from the largest technology companies during third-quarter earnings season.
The question is no longer simply whether AI spending continues.
It is whether that spending continues accelerating fast enough—and ultimately generates enough earnings—to support valuations while the risk-free rate remains above 5%.
Third-quarter corporate earnings provide the next major test.
S&P 500 companies are currently expected to report more than 30% year-over-year earnings growth, according to LSEG data cited by Reuters. PepsiCo and Delta Air Lines are among the large companies reporting next week, before major U.S. banks begin the broader earnings season the following week.
The market enters that period from an unusual position.
Economic growth remains sufficiently resilient to support corporate profits, yet persistent inflation and elevated energy costs are keeping interest rates high. Meanwhile, Friday’s weak employment report showed that the labor market is losing momentum.
That leaves investors balancing three forces simultaneously: slowing employment, persistent inflation and exceptionally strong corporate earnings expectations.
The Federal Reserve adds another variable.
After September’s jobs report, traders were pricing roughly an 80% probability that the Fed leaves rates unchanged in October, up from approximately 74% before the employment numbers were released.
Minutes from the Fed’s September meeting are due Wednesday and could provide additional information about policymakers’ willingness to tighten monetary policy again later this year.
For Wall Street, however, Treasury yields may be the more immediate constraint.
The S&P 500 has demonstrated remarkable resilience despite the bond selloff. But maintaining that resilience becomes increasingly difficult if the 10-year yield remains above 5% while companies continue issuing enormous amounts of debt to finance AI infrastructure.
That makes the beginning of the fourth quarter a significant inflection point.
If corporate earnings and AI-related investment continue exceeding expectations, equities may be able to absorb unusually high borrowing costs.
If earnings disappoint or hyperscalers begin moderating capital spending, the combination of elevated valuations and 5%-plus Treasury yields could become substantially more difficult for investors to ignore.