Kotak Mahindra Bank reported stronger-than-expected quarterly earnings as rapid loan growth and lower provisions strengthened profitability at one of India’s largest private lenders.
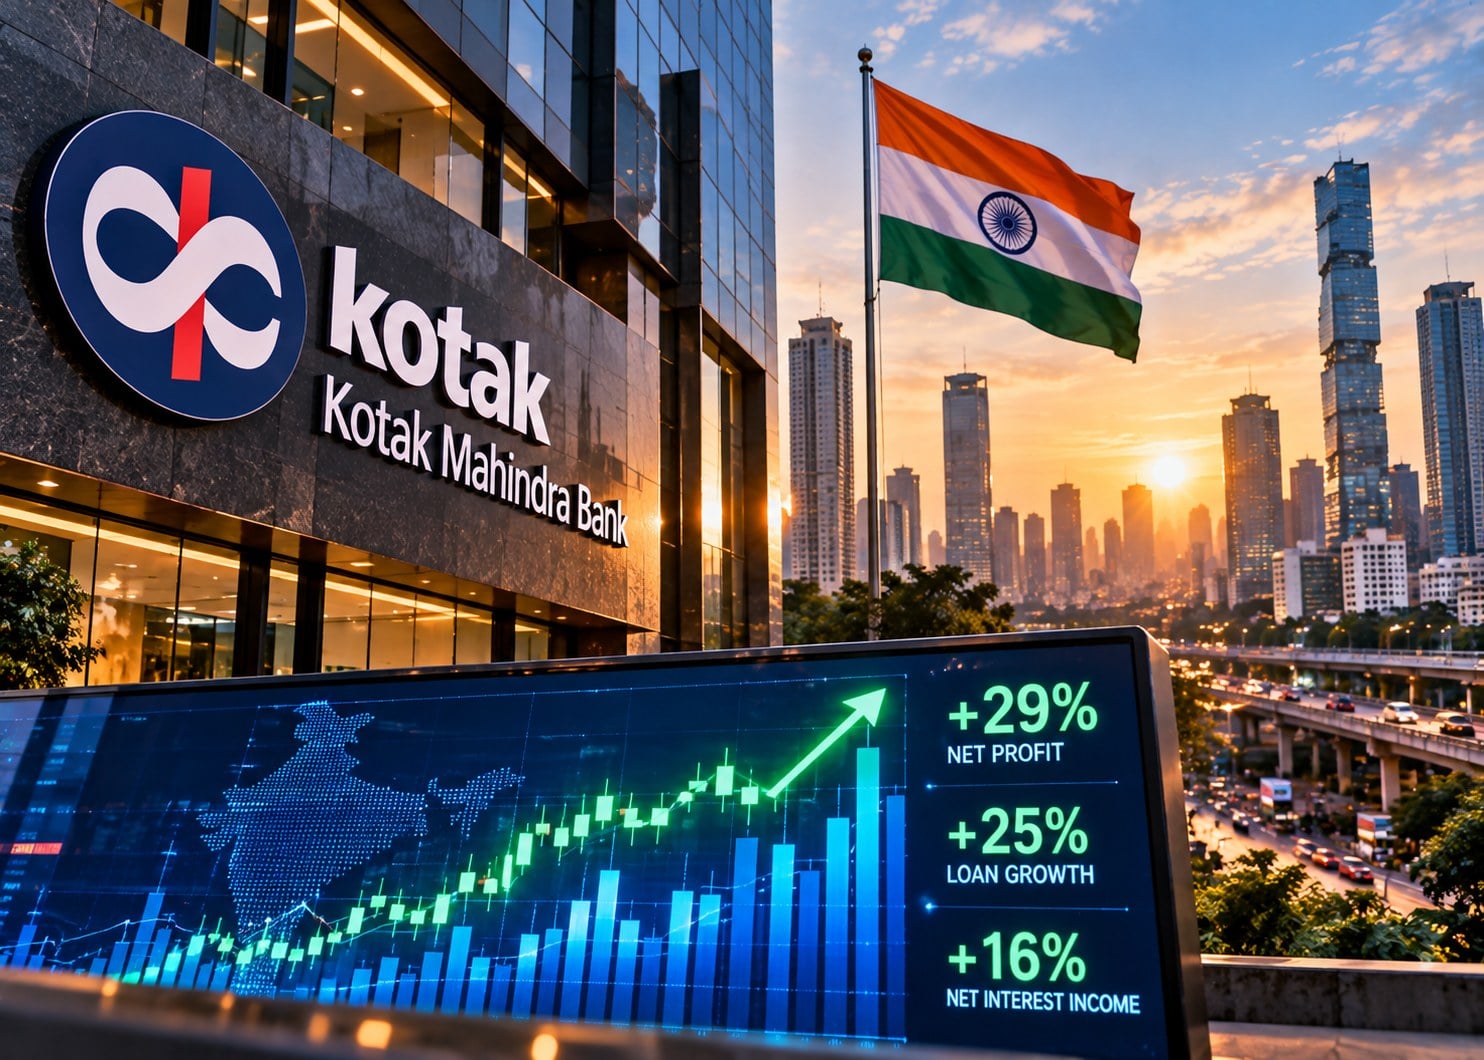
Standalone net profit increased 29% from a year earlier to 42.11 billion rupees, or approximately $443.5 million, for the quarter ended September.
Analysts surveyed by LSEG had expected approximately 41.04 billion rupees.
Net interest income increased about 16% to 84.6 billion rupees, supported by a roughly 25% increase in domestic loans.
Deposits expanded approximately 23%.
Credit costs also provided support.
Provisions for potential bad loans and other losses declined 15% to 8.04 billion rupees.
Asset quality improved, with the gross non-performing-loan ratio falling to 1.04% from 1.18% three months earlier.
One important pressure point remained.
Kotak’s net interest margin declined to 4.31% from 4.53% in the previous quarter, partly reflecting the bank’s efforts to attract foreign-currency non-resident deposits.
The results reinforce the broader strength of Indian credit demand.
Corporate and retail borrowing has remained robust, while measures introduced by the Reserve Bank of India have encouraged banks to attract additional foreign-currency deposits.
For investors, the question is whether rapid loan growth can continue offsetting margin compression.
Strong credit expansion and improving asset quality support earnings, but sustained pressure on lending spreads could eventually limit how much of that growth reaches the bottom line.