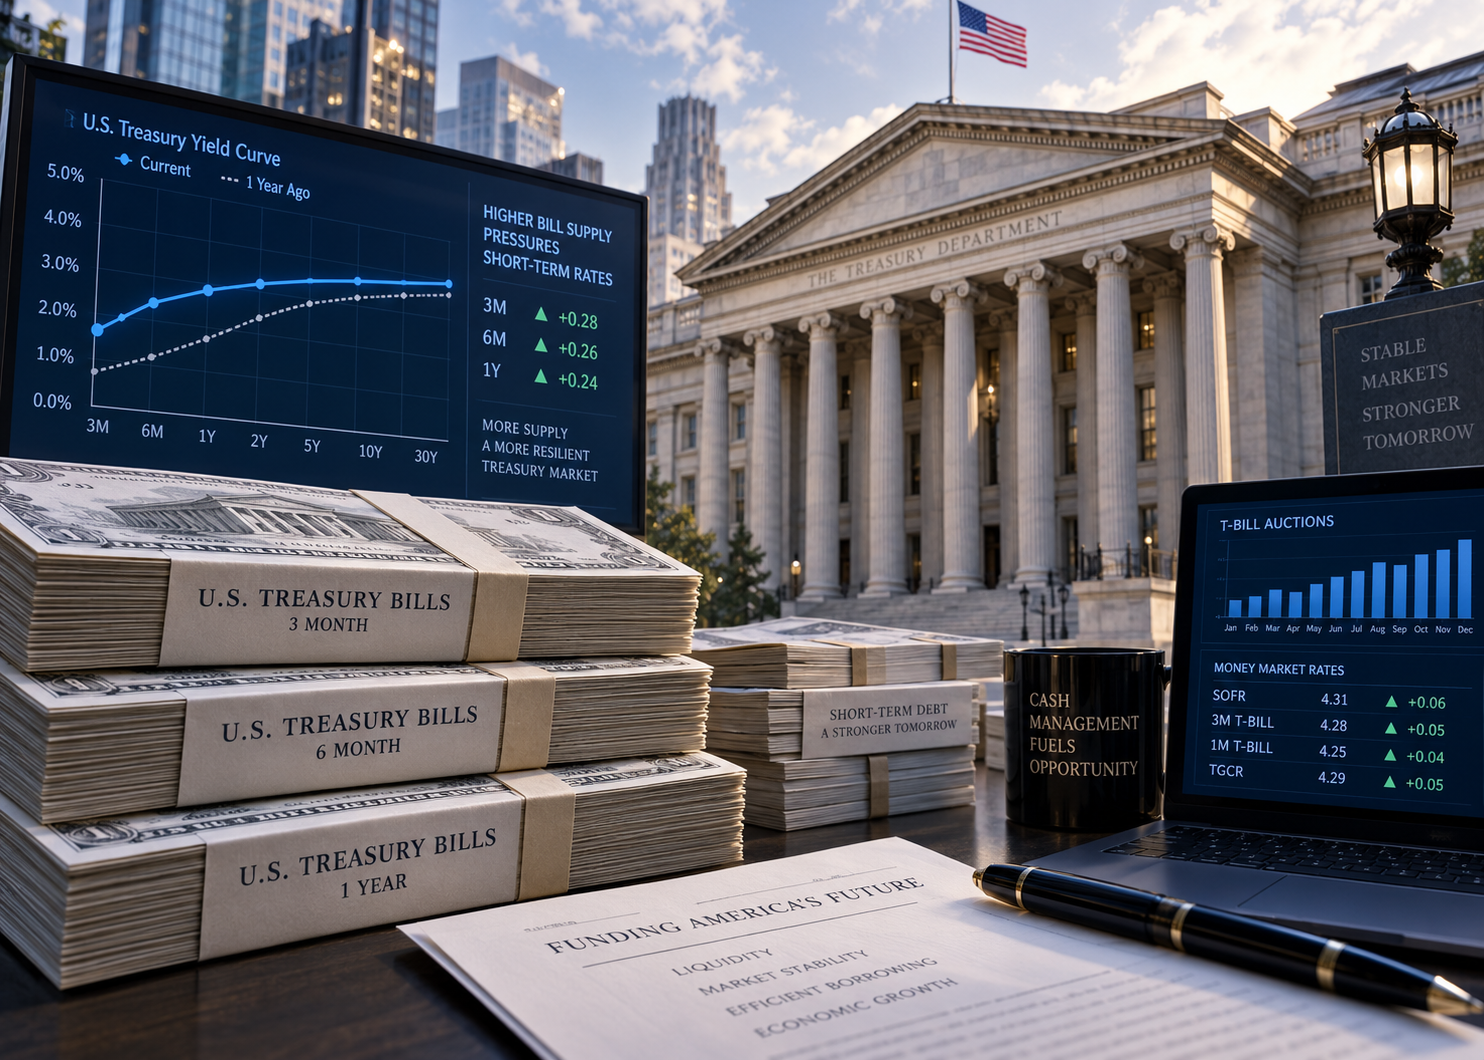
Wall Street’s largest banks expect the U.S. Treasury to raise roughly $1 trillion in additional financing through short-term Treasury bills over the coming year, potentially pushing the government further toward debt that must be refinanced frequently.
Bank of America projects about $1.07 trillion in net bill issuance during the fiscal year ending September 2027. JPMorgan estimates approximately $1.09 trillion during calendar 2027, while Goldman Sachs forecasts roughly $961 billion. These are bank forecasts rather than an announced $1 trillion Treasury issuance plan.
The projections matter because Treasury bills mature in one year or less, meaning a greater reliance on bills can reduce the amount of long-term borrowing locked in at today’s elevated yields but also requires the government to refinance a larger portion of its debt more frequently.
Bank of America expects the outstanding stock of Treasury bills to approach $8 trillion by September 2027, representing roughly 24.3% of marketable Treasury debt. Goldman Sachs projects a similar share next year and sees bills approaching 25% of marketable debt in 2028.
The shift comes as U.S. long-term borrowing costs remain elevated. Treasury yields have recently traded near levels not seen in almost two decades, increasing the cost of issuing longer-dated government debt.
Official Treasury financing plans already point to substantial borrowing requirements.
The Treasury Department expects $739 billion in privately held net marketable borrowing during the July–September quarter and another $628 billion during October–December.
Treasury’s August quarterly refunding statement also said that regular weekly bill auctions and cash-management bills would continue to absorb part of the government’s financing needs. It said current coupon auction sizes were expected to remain broadly unchanged for several quarters while Treasury continued monitoring growing private-sector demand for bills and Federal Reserve bill purchases.
That distinction is important.
The projected $1 trillion bill wave is not simply a story about the total amount Washington is borrowing. It is also about where on the maturity curve that borrowing occurs.
Short-term bills can be attractive when long-term rates are high because Treasury avoids locking in elevated borrowing costs for decades. But the tradeoff is greater refinancing exposure: bills mature quickly and must repeatedly be replaced with new securities.
That makes future interest costs more sensitive to short-term rates.
Demand for bills remains substantial. Money-market funds, institutional cash investors and the Federal Reserve are significant buyers of short-term government securities, helping provide a deep pool of demand for additional issuance. U.S. money-market fund assets have grown dramatically in recent years, reinforcing the importance of bills within the financial system.
For markets, the consequences extend beyond government financing.
A larger bill supply can influence money-market liquidity, short-term yields, bank reserves and the allocation of trillions of dollars held by money-market funds and other cash investors.
The longer-term question is whether heavier reliance on short maturities remains manageable if interest rates stay high.
If borrowing requirements remain large while refinancing occurs more frequently, changes in Federal Reserve policy and short-term Treasury yields could move through the government’s interest expense more quickly than under a longer-maturity funding structure.
For investors, the coming Treasury issuance cycle will therefore be about more than the headline amount of debt.
The maturity of that debt — and who absorbs it — may become just as important as how much Washington ultimately borrows.