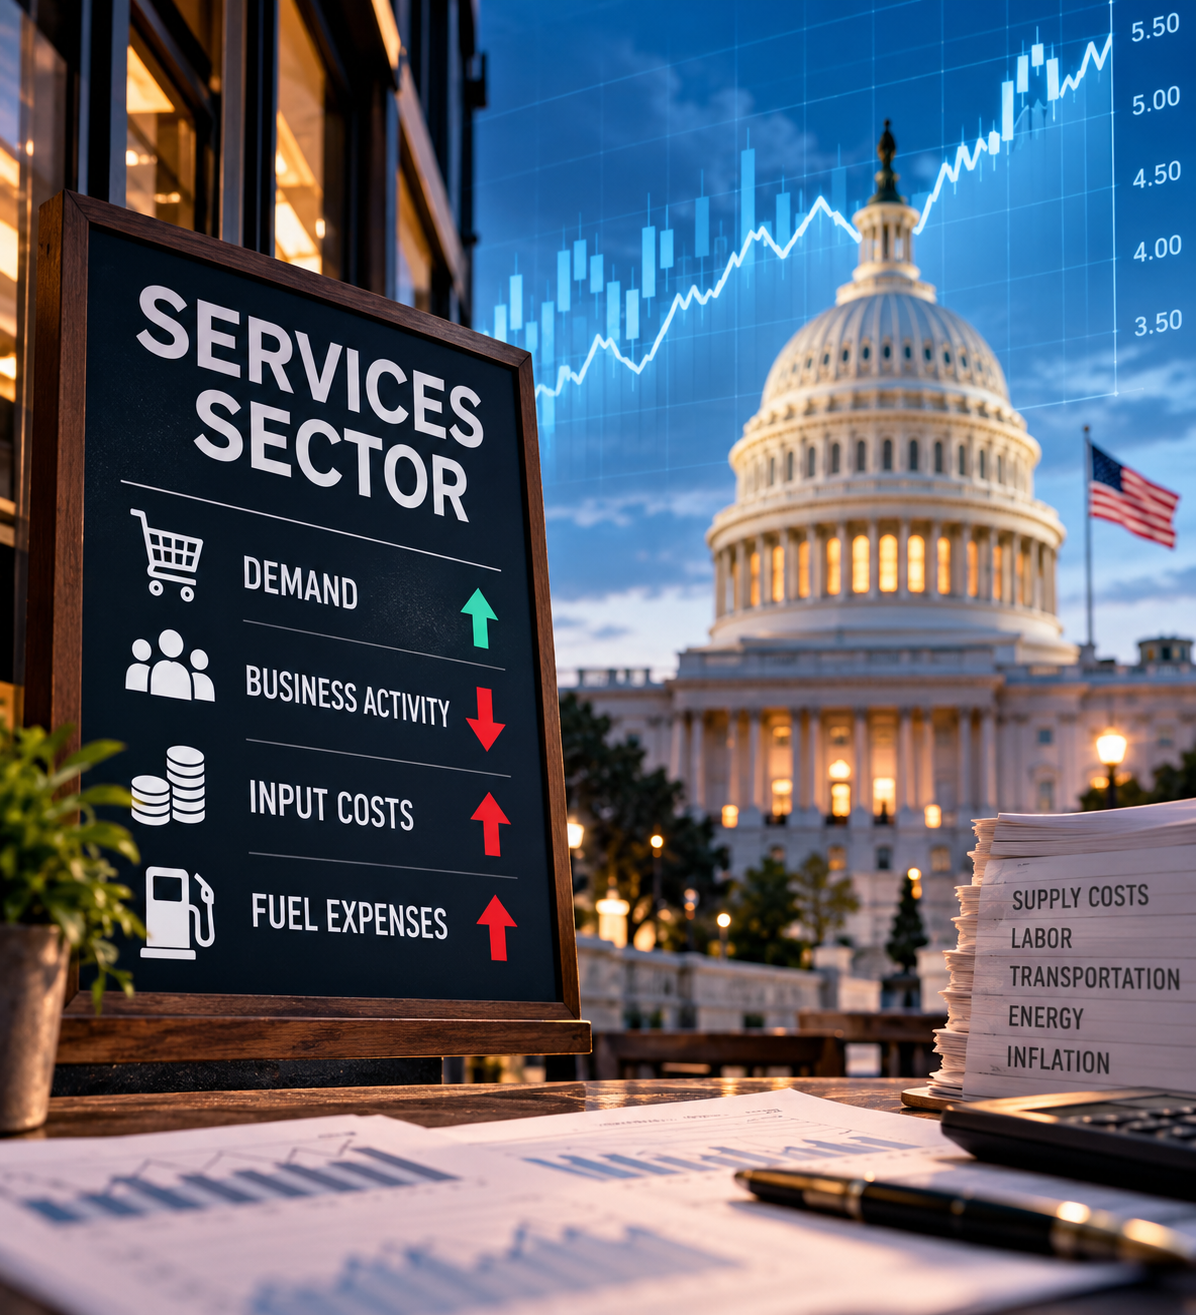
U.S. services-sector activity slowed in September while input-price pressure climbed to its highest level in more than four years, presenting the Federal Reserve with another uncomfortable combination of softer growth and persistent inflation.
The Institute for Supply Management’s latest services survey showed demand remained resilient but businesses faced mounting supply-chain and cost pressures. Respondents frequently cited elevated fuel expenses.
The inflation signal is particularly important because services account for the majority of U.S. economic activity and have been one of the more persistent components of the post-pandemic inflation cycle.
The report arrived as financial markets reassessed the outlook for monetary policy following weaker U.S. employment data.
That weaker labor backdrop has reduced expectations for an October Federal Reserve rate increase, but the services data complicates the picture by showing that inflationary pressure has not disappeared.
Treasury yields remained elevated Monday while the dollar strengthened and technology shares helped push the Nasdaq to a record.
The combination illustrates the policy problem facing the Fed: slowing parts of the economy argue against excessive tightening, while persistent price pressure limits policymakers’ ability to declare the inflation fight finished.
For investors, the next test will be whether higher business input costs migrate into consumer prices or instead compress corporate margins.
Upcoming inflation and employment data will therefore remain central to expectations for the Fed’s remaining 2026 meetings.